- contact@insightkycai.com
InsightKYC · know-your-customer, prepared by agents
Every KYC case prepared. Every decision yours.
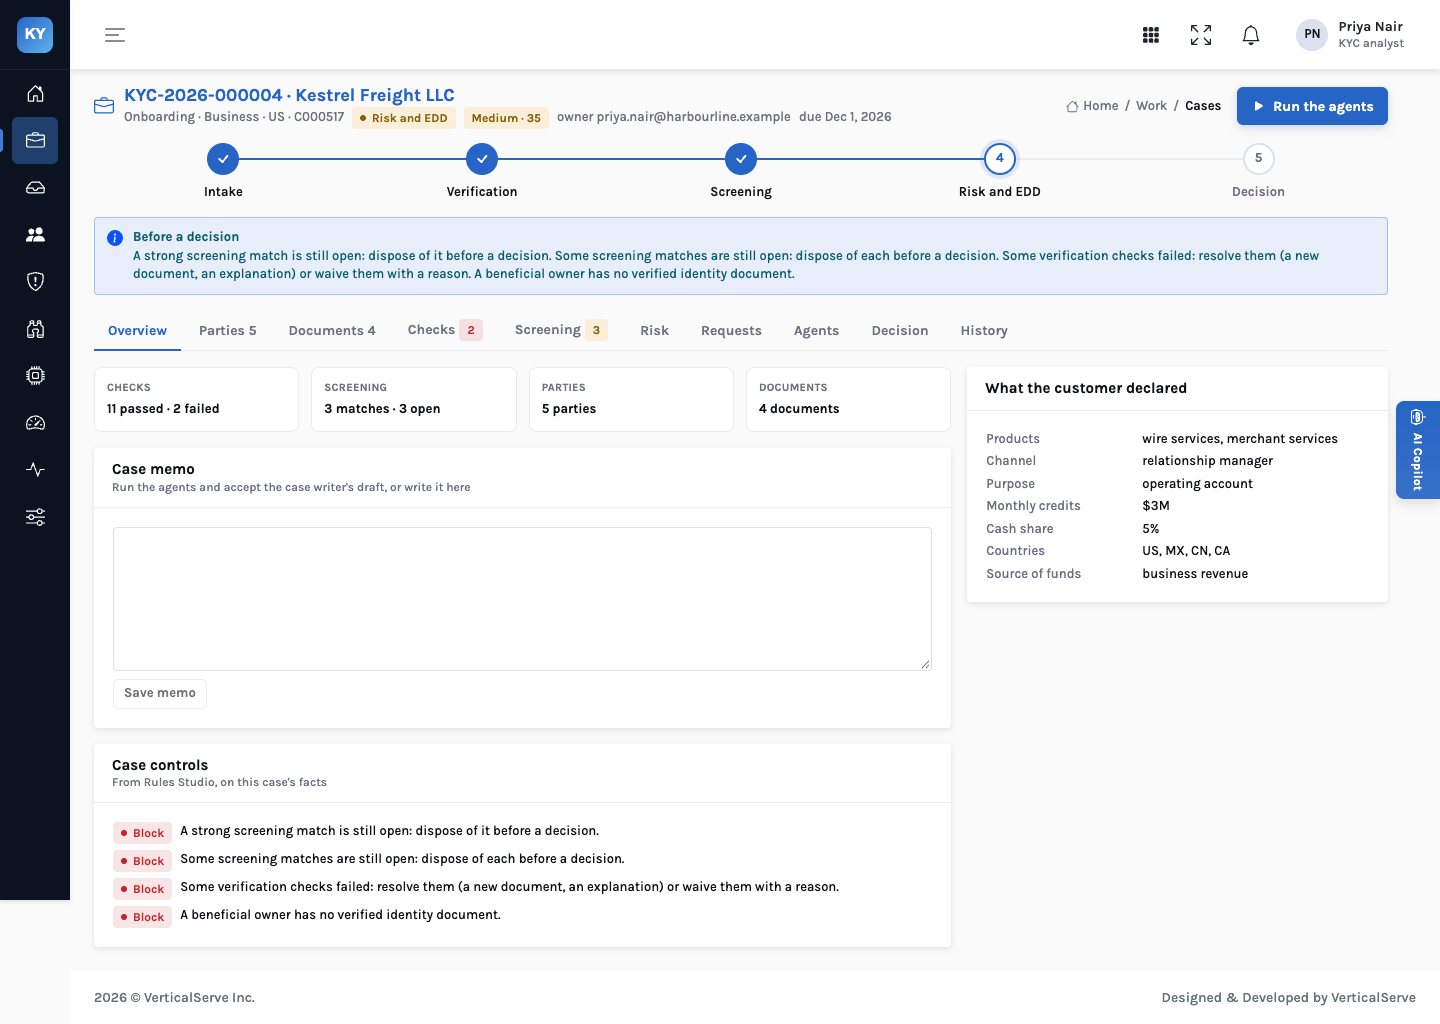
InsightKYC reads the passport and the certificate of incorporation, quoting every field from its line. It walks the company registry down every chain to the people who really own the customer, and screens each of them against sanctions, PEP and adverse-media lists with a score that shows its work. It rates the risk with a reason for every point and drafts the memo. Then it stops, and an analyst decides.
- Every field quoted from its line
- Owners found through the registry
- People decide, on the record
What a case is built from
Passports (ICAO 9303 MRZ)Driver’s licencesUtility billsBank statements
Certificates of incorporationRegisters of membersCompany registry
Sanctions listsPEP listsAdverse mediaCore banking transactionsYour risk policy
The problem
KYC teams don’t lack rules. They lack time to apply them the same way every time.
Most of an analyst’s day is preparation: retyping a passport, opening a registry extract, multiplying percentages down an ownership chain, clearing screening matches that are plainly someone else. The judgement, which is the part only a person can do, gets whatever time is left. Onboarding waits, and the file an examiner reads later doesn’t say why.
Preparation
The work before the decision
Reading documents, comparing them with the application, chasing the missing one. It is necessary, repetitive, and the reason a simple onboarding takes days.
Ownership
The owner nobody declared
An application names one shareholder. The registry shows a holding company offshore, and behind it someone who owns more than anyone on the form. Finding that by hand means multiplying down every chain.
Evidence
“Why did we approve this?”
When a customer goes wrong, the question is what the bank knew at the time. A note that says “screening clear” doesn’t answer it. A record of every match, disposition and control does.
How it works
Intake → Verify → Screen → Rate → Decide
One case for every onboarding, periodic review and event-driven review. Ten agents prepare each stage. A person accepts, rejects or asks about what they prepared, and makes every decision that matters.
1
Intake
A case opens from an application, from the customer book when a review falls due, or from a monitoring alert. The intake agent lists what is on file and what is missing.
2
Read and verify
Documents are read into fields, each quoted from its line. Checks compare them with the application: in date, same name and date of birth, MRZ check digits, a recent proof of address, and registry status.
3
Own and screen
The registry is walked down every chain to the beneficial owners. Every party is screened against sanctions, PEP and adverse media, and each match shows how name, date of birth and nationality compare.
4
Rate and EDD
A points model rates the customer, with the reason for every factor. High risk and PEPs need enhanced due diligence; prohibited countries and industries block approval.
5
Decide
Case controls from Rules Studio say what blocks a decision. High risk needs a second person. The decision record keeps every control, the rating and each disposition as they stood.
Beneficial ownership
The application named one owner. The registry found another, at 56%.
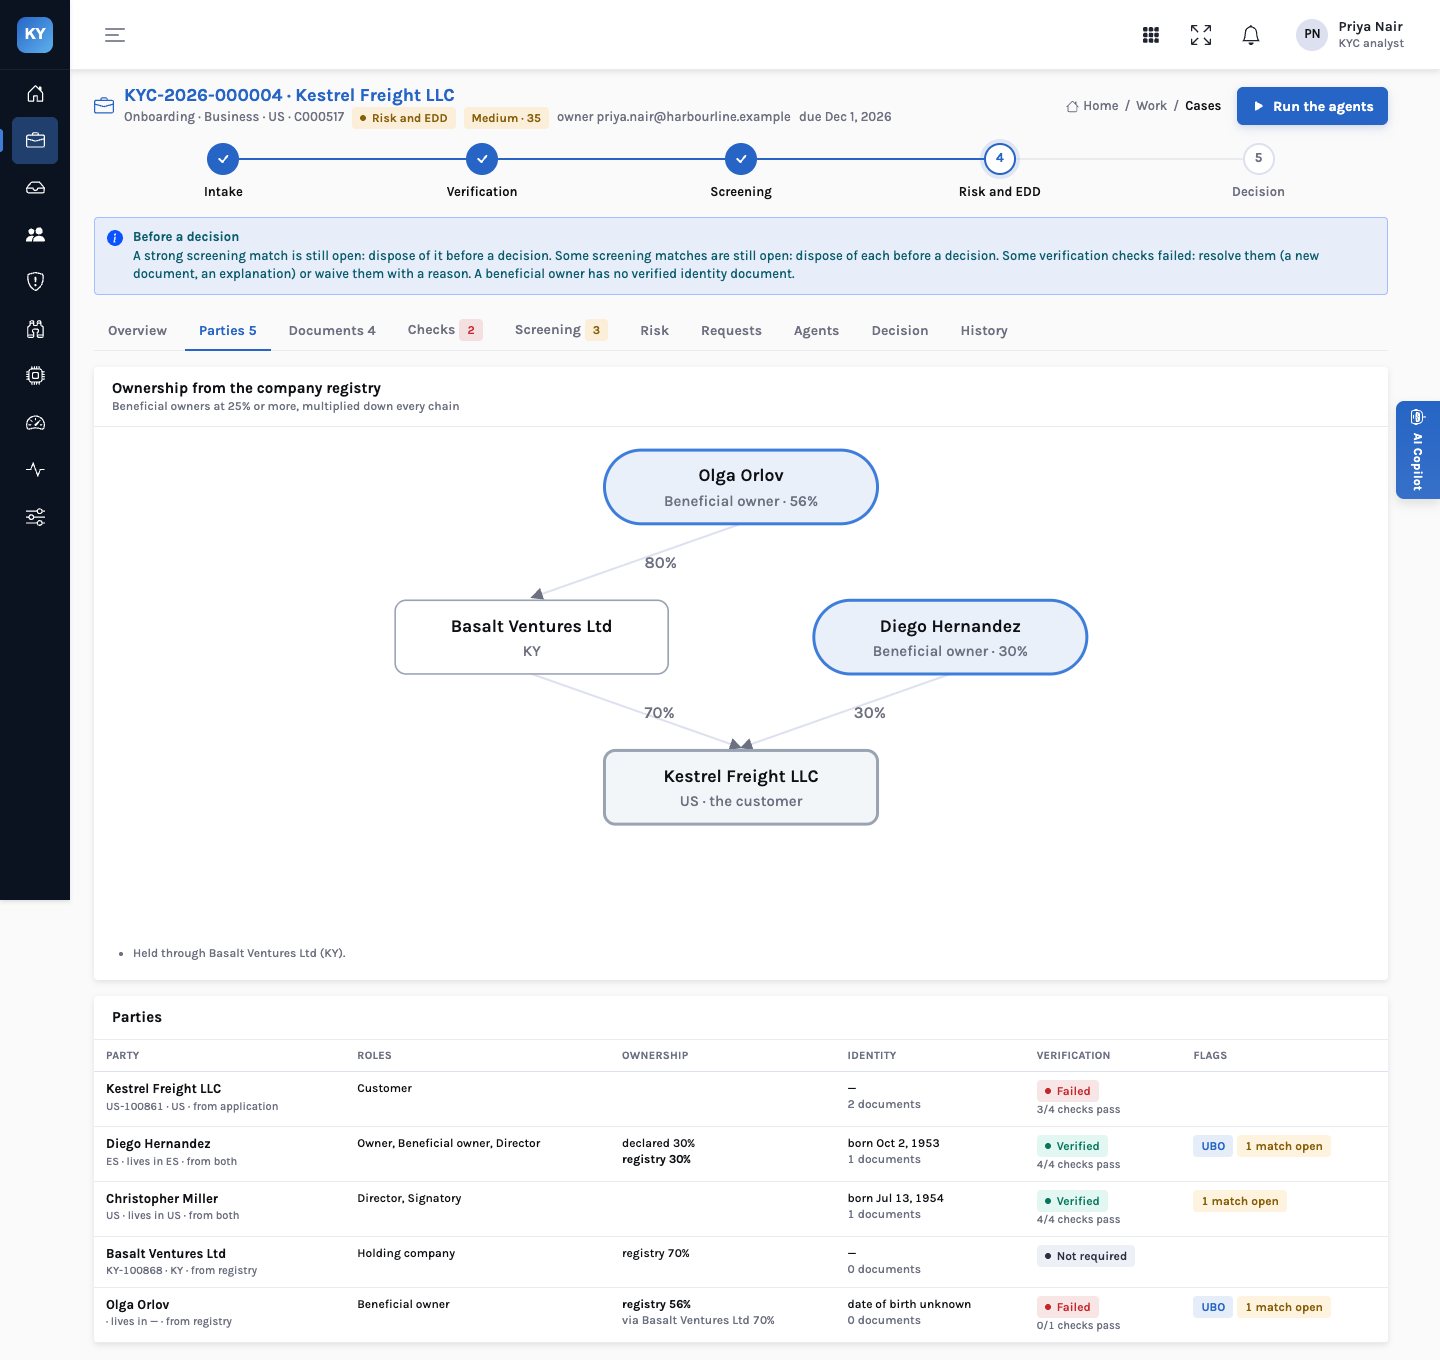
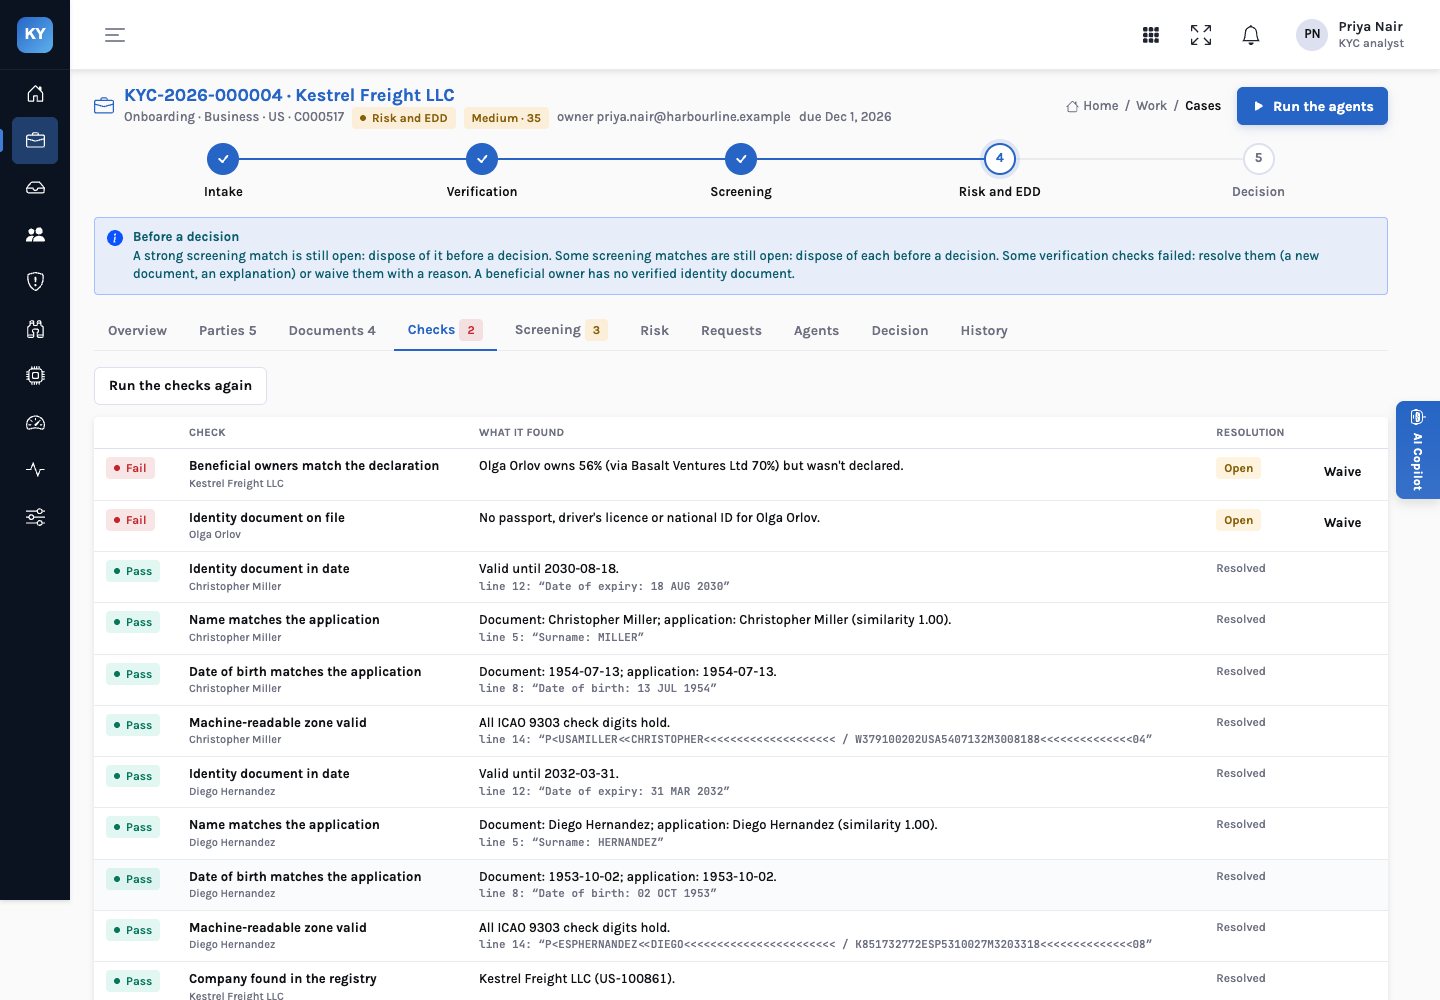
From the demo bank’s data: Kestrel Freight LLC declared Diego Hernandez at 30%. InsightKYC walked the registry, found a Cayman Islands holding company owning the other 70%, and the person behind it. It multiplies every chain, adds the holding company and its owner to the case, and raises the difference as a failed check.
Not declaredOlga Orlovowns 80% of Basalt Ventures Ltd
Holding companyBasalt Ventures Ltd (KY)owns 70% of the customer
The customerKestrel Freight LLC (US)applied for a business account
Effective80% × 70% = 56%above the 25% threshold: a beneficial owner
Screening and risk
Scores that show their work
An analyst can only disagree with a score they can read. Every screening match and every risk rating in InsightKYC comes with the reasons that produced it.
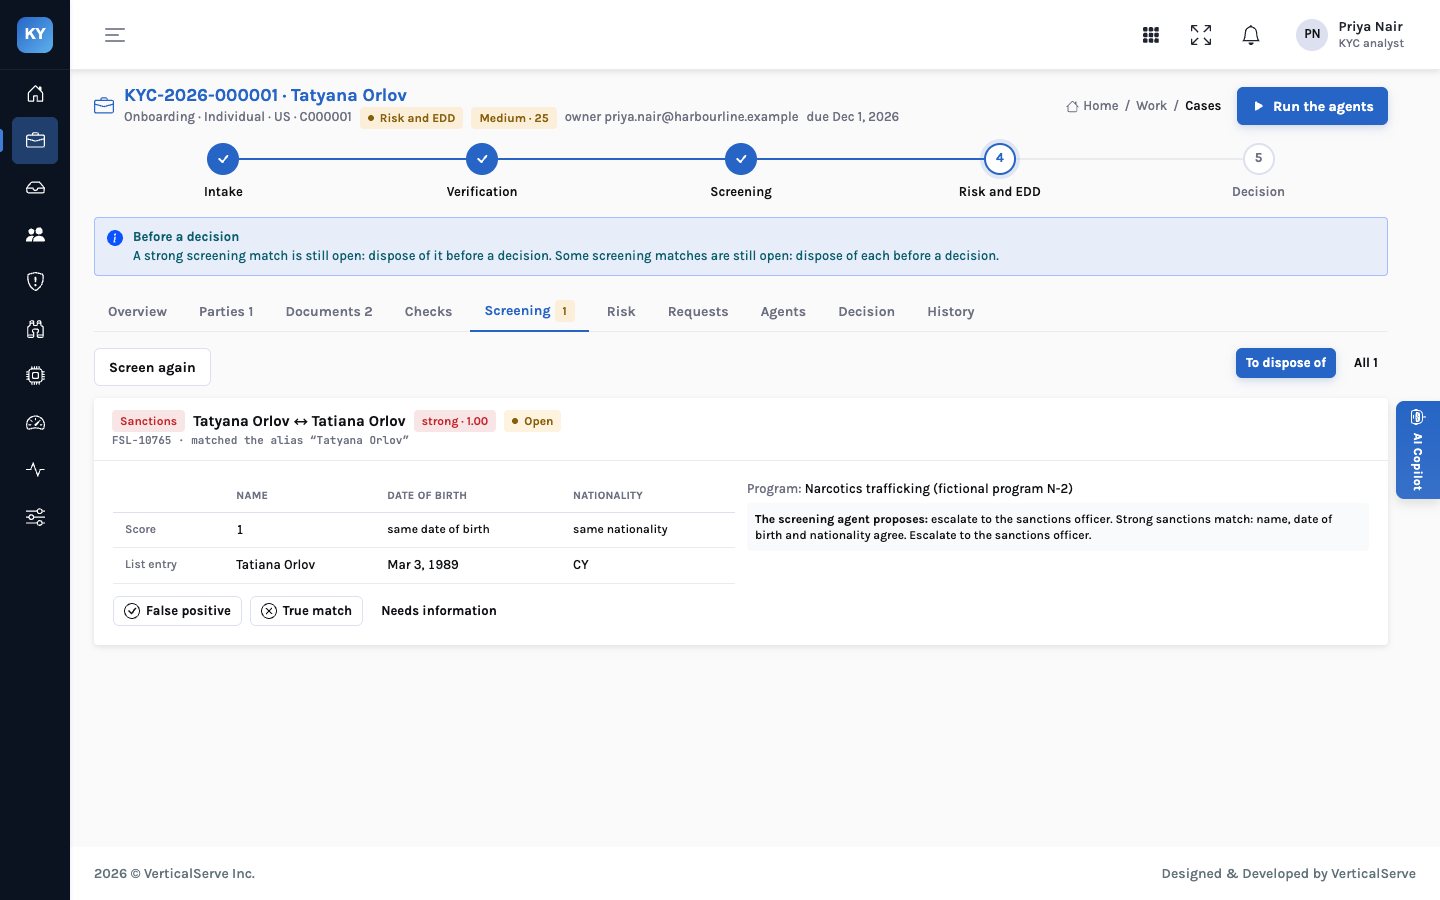
A sanctions match
Why this one reached the analyst, and eight didn’t
The demo bank’s fictional sanctions list holds nine entries that look like Tatyana Orlov. Eight share the first name but carry a different surname, so they never reach the queue. The one left agrees on everything.
- Namematched the alias “Tatyana Orlov” of entry FSL-107651.00
- Date of birthsame date: 3 March 1989agrees
- Nationalitysame countryagrees
- Strong match → escalate to the sanctions officerstrong
The agent proposes a disposition. It cannot clear a strong sanctions match; a person records the outcome with a reason.
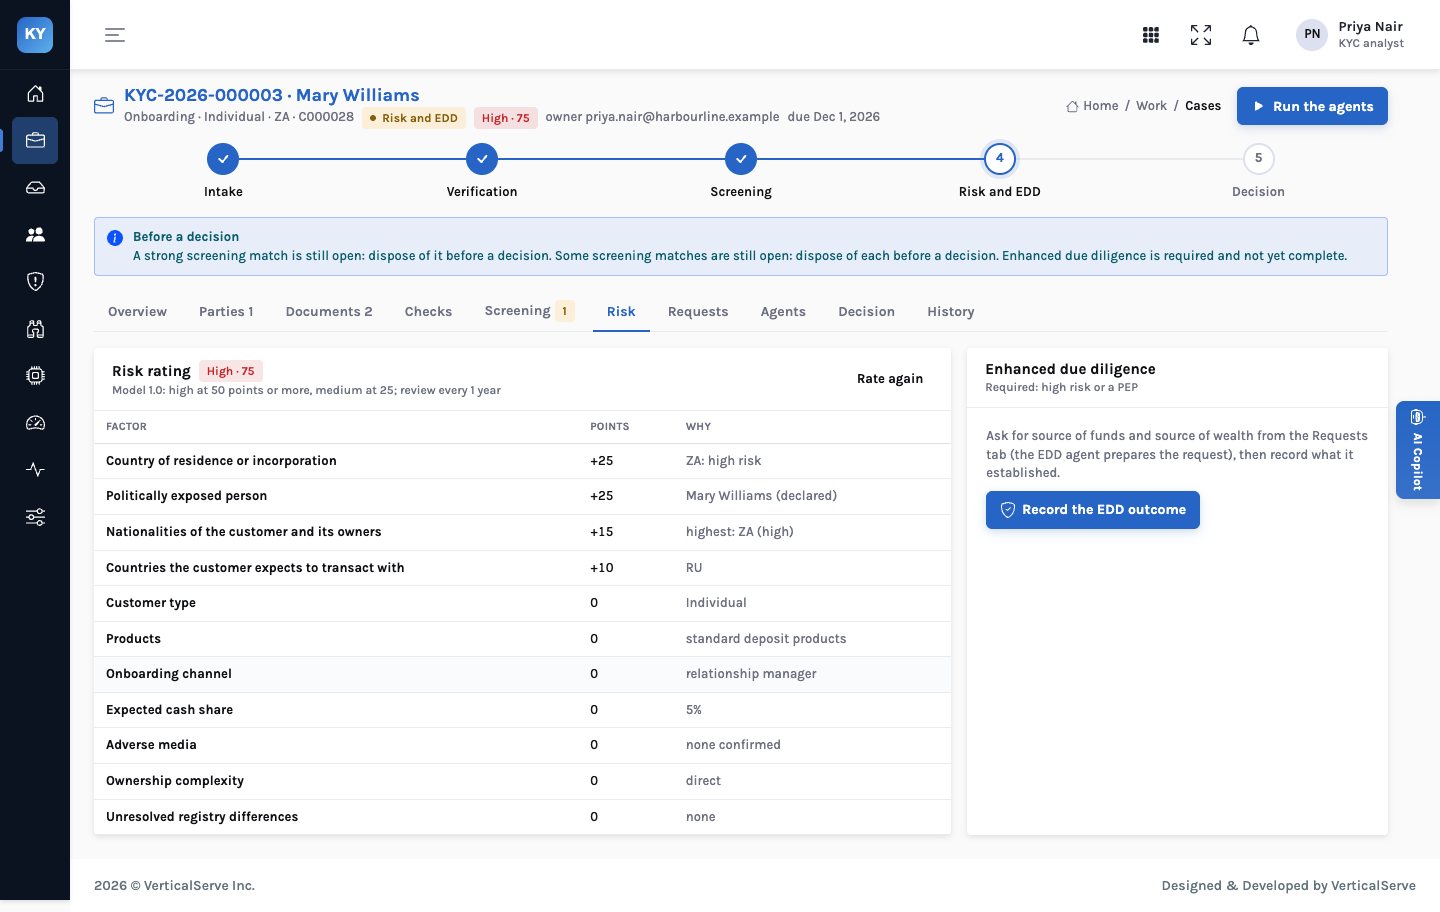
A risk rating
High at 75 points, with every point explained
Mary Williams, a declared politically exposed person living in South Africa, from the demo bank. The model is a points table you set; the thresholds here are illustrative.
- Country of residenceZA is rated high risk in the policy+25
- Politically exposed persondeclared, and confirmed by screening+25
- Nationalities of the customer and ownershighest: ZA (high)+15
- Countries she expects to transact withRU+10
- Rating → high: EDD and four eyes75
High at 50 points or more, medium at 25. A lead can override the rating, with a reason that goes on the decision record.
AI agents
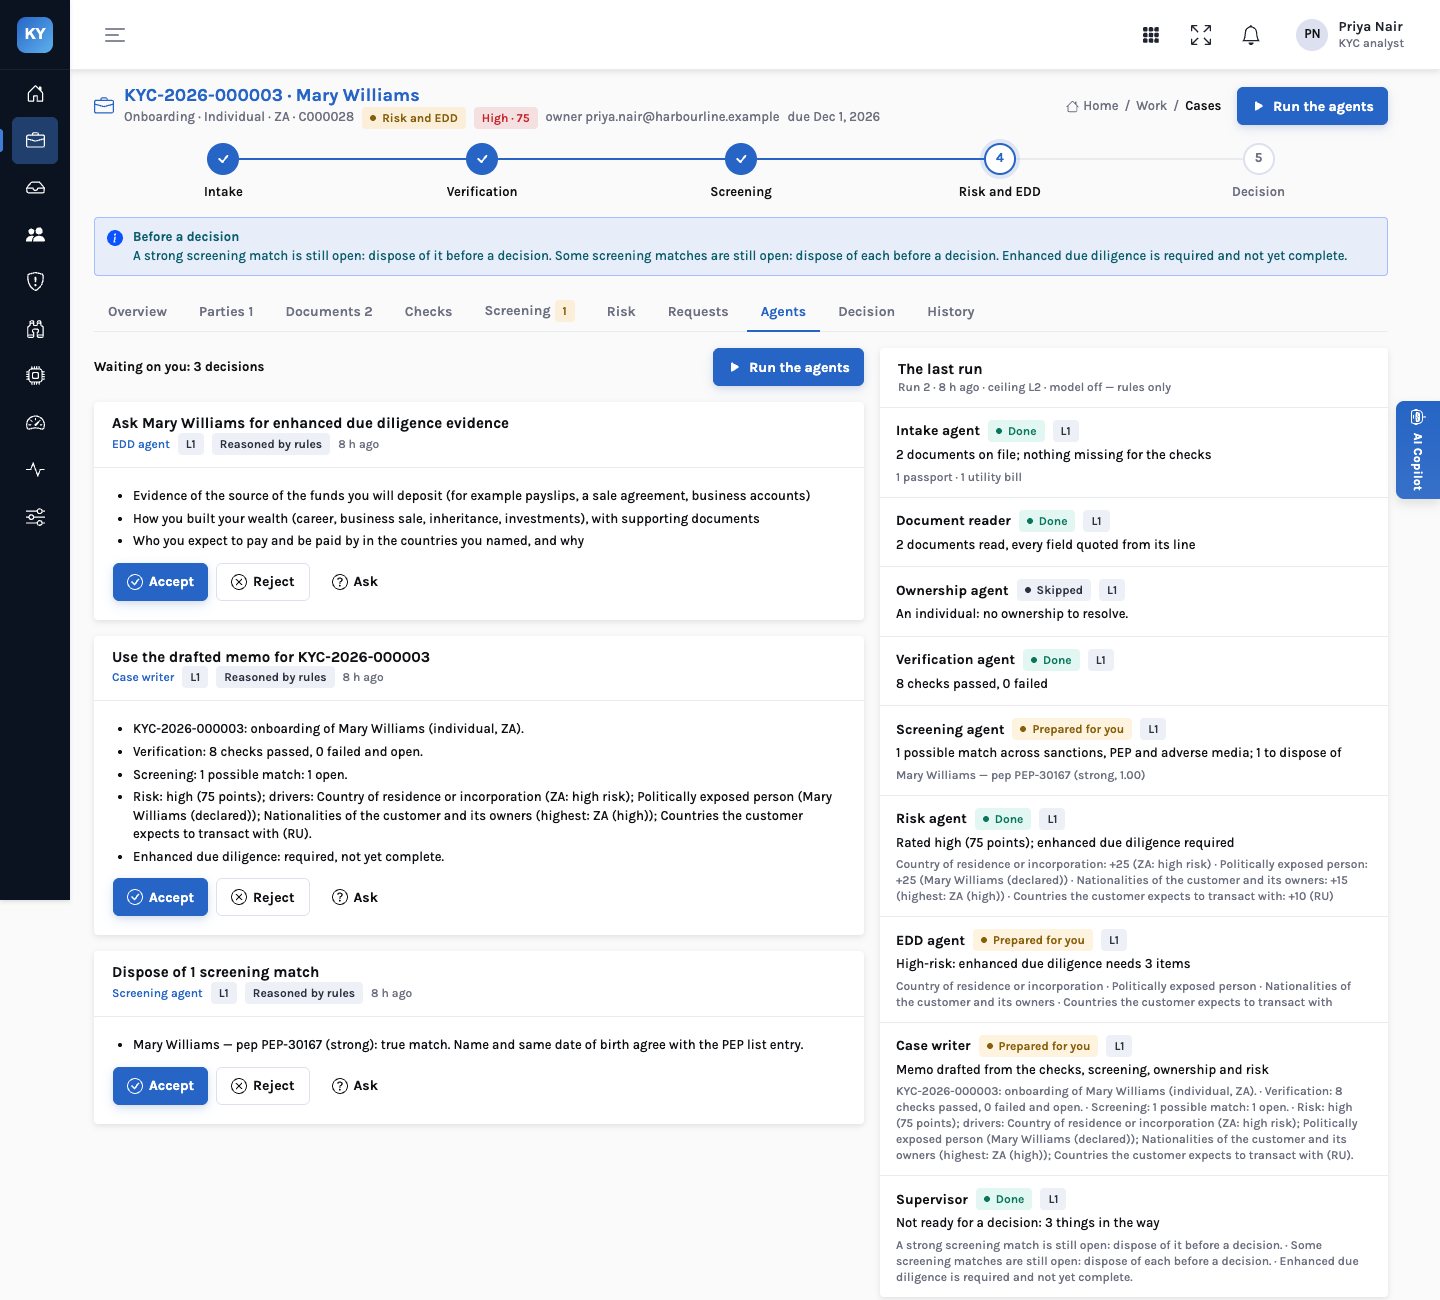
Ten agents prepare. Nobody’s job is to click “approve” on a machine.
Each agent does one stage of the case and stops at a prepared decision: a request to send, a memo to accept, dispositions to apply. You accept, reject or ask a question. Every answer goes on the record, and how often people agree is how an agent earns more autonomy.
- Intake, document reader, ownership, verification, screening — gather the facts, each quoted from where it came from
- Risk, EDD, case writer, supervisor — rate it, say what is missing, draft the memo, and say whether the case is ready
- Monitoring — reads every active customer’s transactions against what they declared
- Never on their own — clearing a sanctions match, waiving a check, sending to a customer, or deciding a case
- Model optional — with the language model off, every agent runs on its rules and says so
Asking the customer
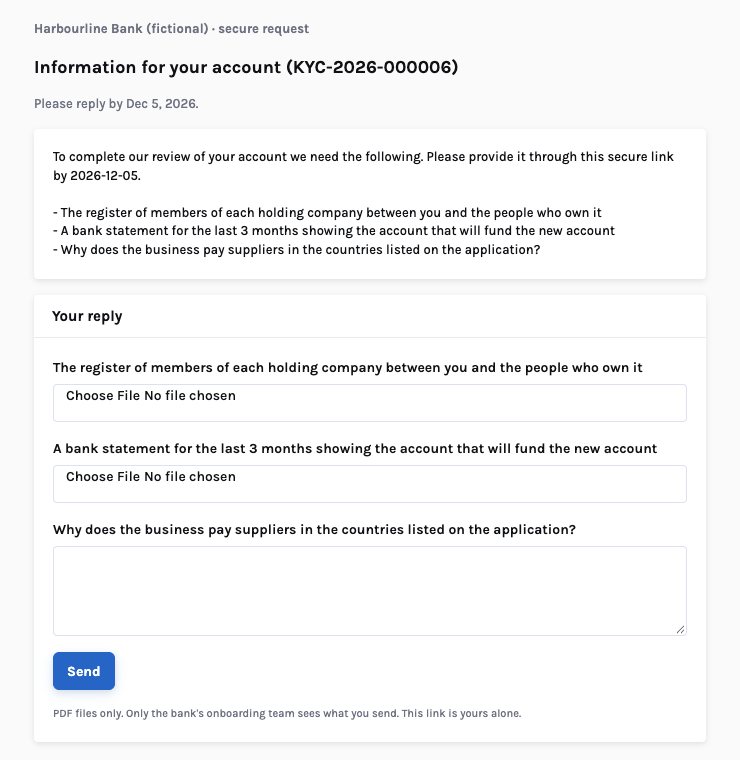
The request is drafted for you. Nothing leaves until you send it.
When something is missing, the agent that noticed drafts the request. It is held on the case for an analyst to edit and send. The customer answers through their own link, with no account to create, and what they upload is read and checked as it arrives.
- Held for review — every request waits for a person; the agents never send
- One link per request — shown once; InsightKYC keeps only a fingerprint of it
- Questions and files — a text box for each question, an upload for each document
- Read on arrival — uploads become documents, and the checks run again
After onboarding
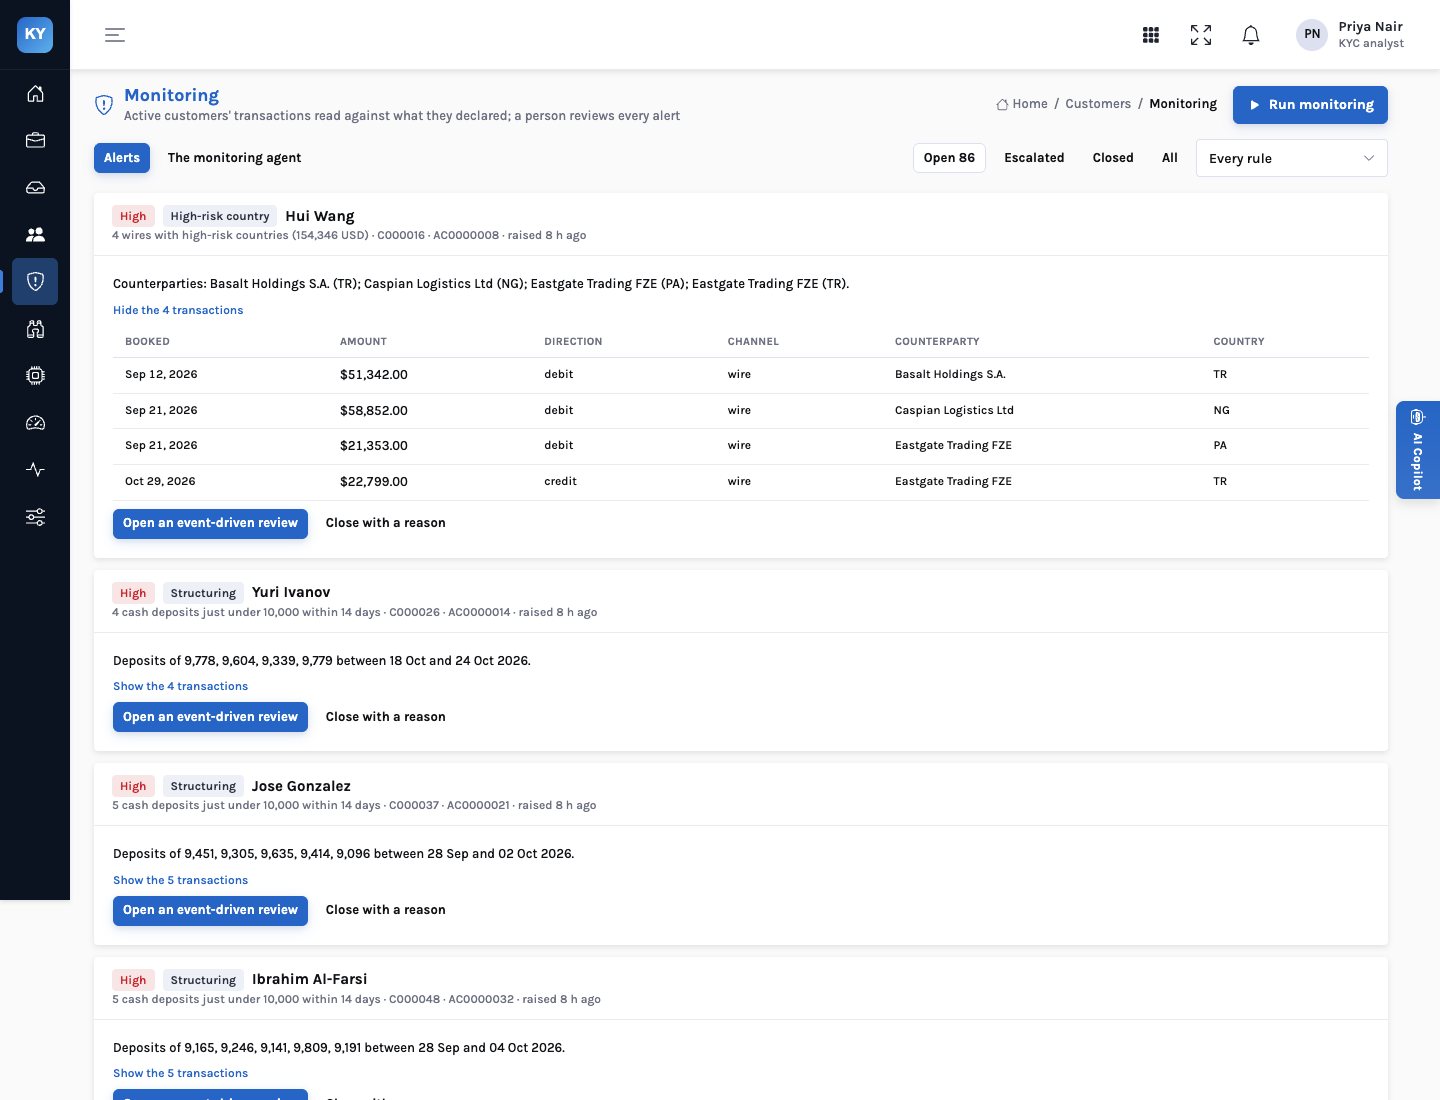
KYC doesn’t end at account opening
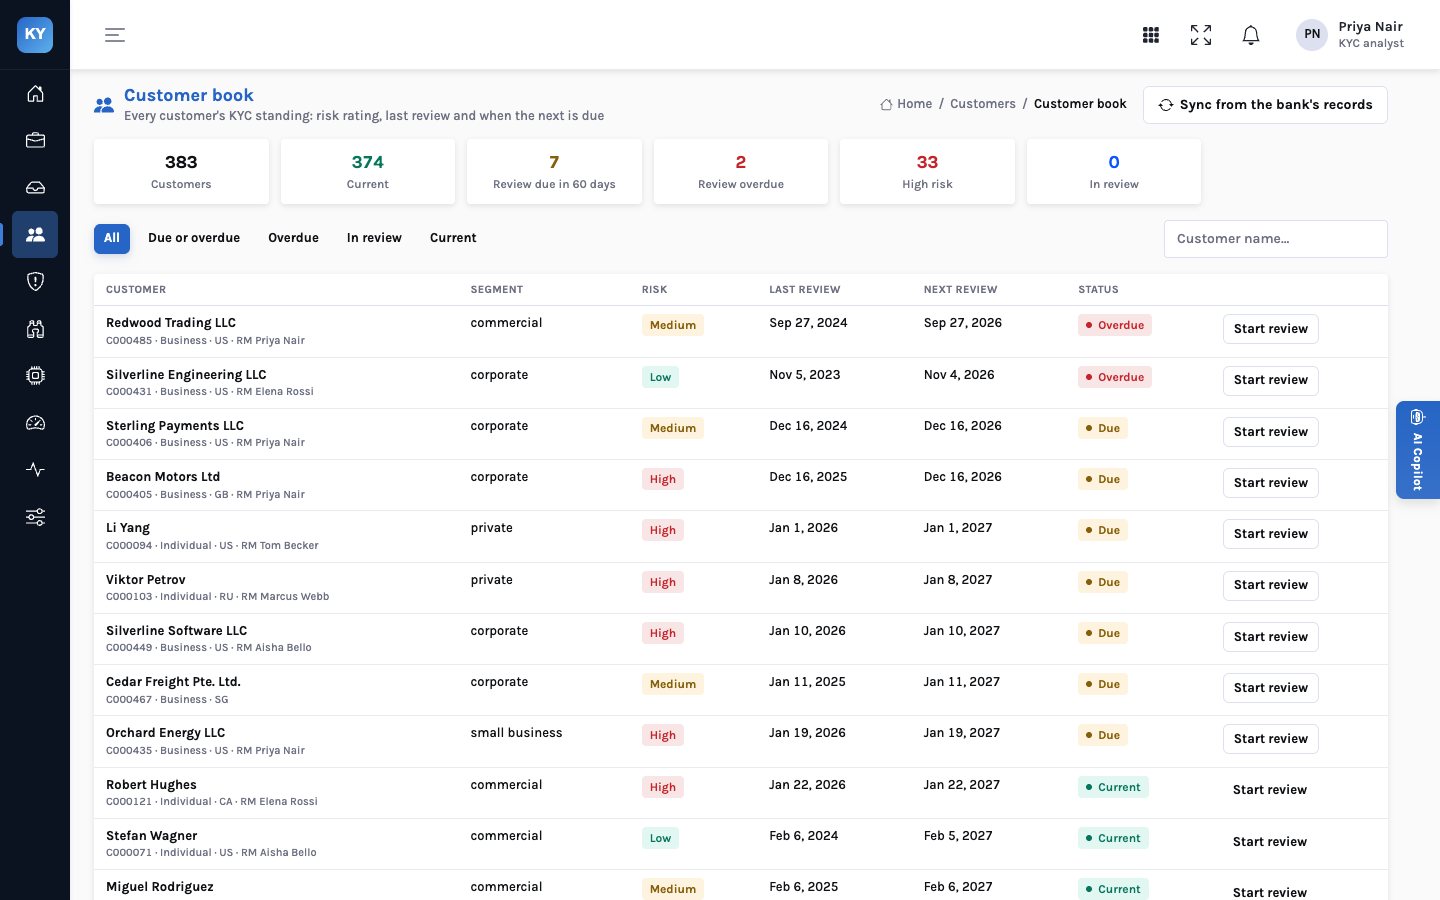
The customer book sets each customer’s next review from its risk rating and turns a due review into a case. Monitoring reads transactions against what the customer declared, and an alert is either closed with a reason or opens an event-driven review.
For compliance leaders
Answers for the examiner, and for the board
The questions a CCO is asked are simple. InsightKYC keeps the evidence for each answer on the case, as it was when the decision was made.
Why did we approve it?
The decision record: who submitted, who approved, every control’s outcome, the rating and each screening disposition, frozen at the decision.
Did two people look?
High-risk and PEP cases are submitted by one person and approved by a lead who isn’t them. The system enforces it.
Is anyone overdue?
The book shows who is current, due soon and overdue, by rating, and opens the review case in one step.
What did the AI do?
Every agent step, what it prepared, who answered and how, and the agreement rate that decides whether it earns more autonomy.
Design & trust
Built to be examined
A Python API, a React app and PostgreSQL, designed to run in your own cloud account against your own systems. Nothing in a case is a value the model made up.
Grounded
No invented facts
A field comes from a document line, an owner from the registry, a match from a list entry. Checks, ownership arithmetic, scores and ratings are deterministic code, not the model.
Read-only sources
Your systems stay yours
InsightKYC reads applications, the registry, lists and transactions from your systems and keeps its own work in its own schema.
Policy
Your rules, in Rules Studio
What blocks a decision and what needs a second person are case controls you can read, test and publish, not code.
Roles
Analysts, leads, auditors
Analysts prepare and submit. Leads approve, override and waive. Auditors read everything and change nothing.